Try it now!
Managing your investments has never been easier!


A comprehensive, mathematically rigorous guide to achieving financial independence and retiring early with an abundant lifestyle.
The short version: Fat FIRE represents the comfortable end of the financial independence spectrum, allowing early retirees to save aggressively now to support higher spending levels later without compromising their standard of living. (Six steps to achieve financial independence and retire early (FIRE) | T. Rowe Price; Fat FIRE: What It Is, How Much You Need & Is It Worth It?)
Financial Independence, Retire Early (FIRE) is not a monolithic movement. The FIRE spectrum ranges from Lean FIRE at the frugal end to Fat FIRE at the comfortable end, with standard FIRE positioned in the middle. This spectrum allows investors to align their savings intensity with their long-term lifestyle expectations.
The core distinction lies in future consumption. Some investors want to save aggressively now so that they can spend more later (known as Fat FIRE). Conversely, others want to save aggressively now and always live frugally, spending at the same lower levels to which they have grown accustomed (known as Lean FIRE). Fat FIRE is designed for those who refuse to compromise on their standard of living in retirement.
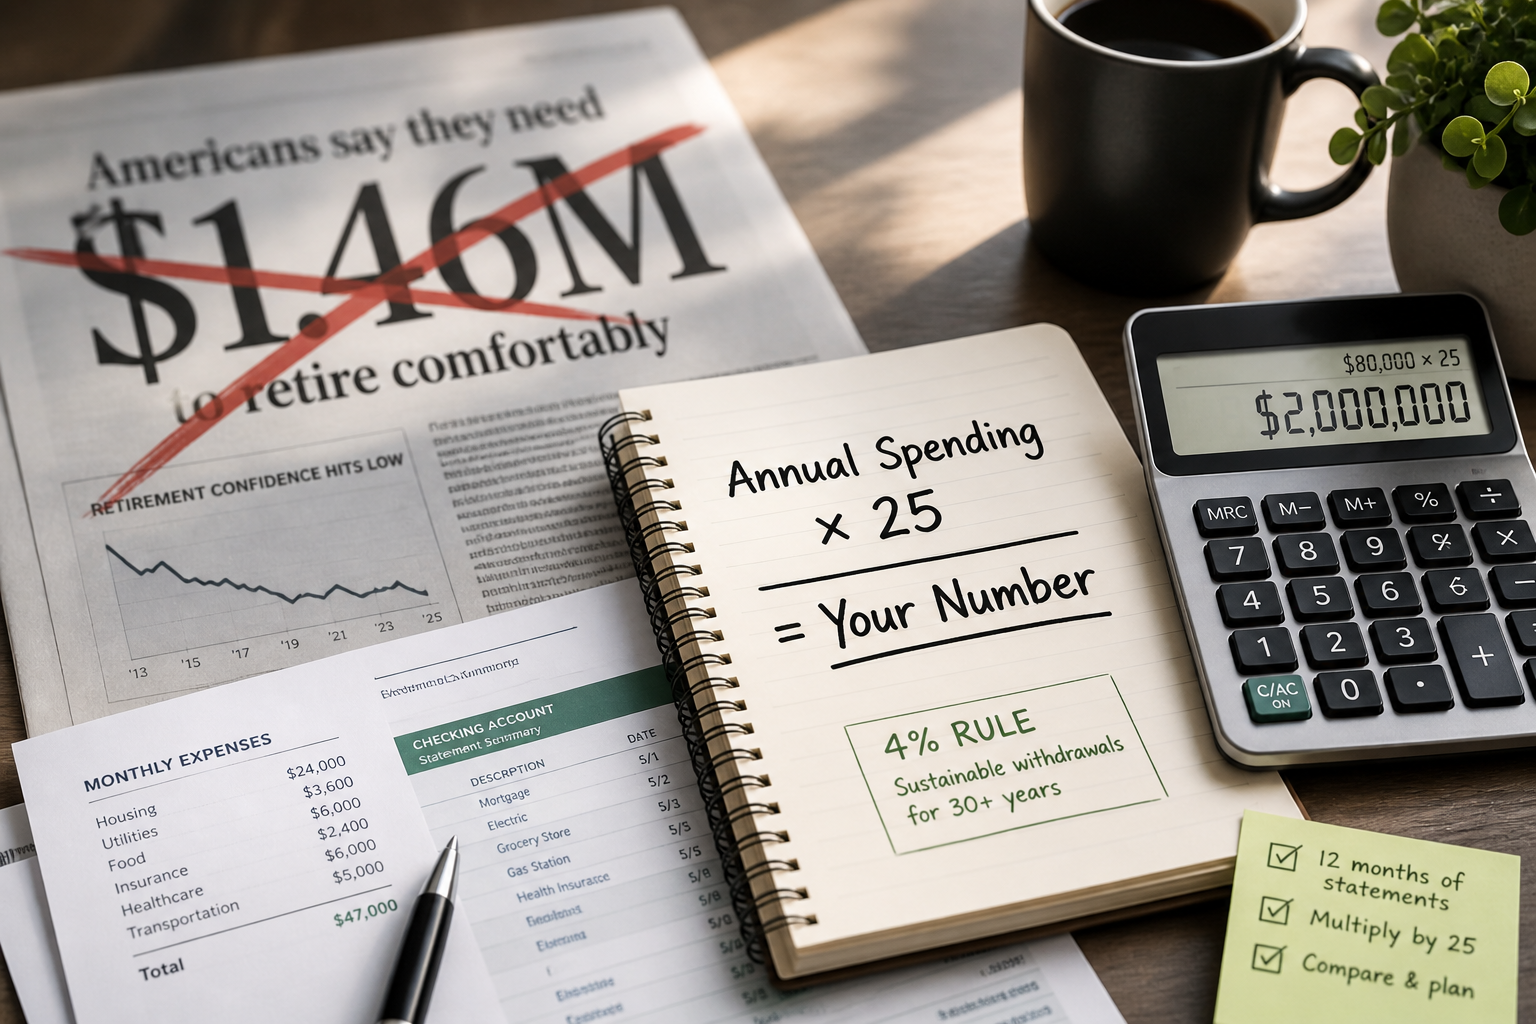
Calculating a Fat FIRE target portfolio relies on the same fundamental mathematical formulas as any other FIRE calculation, but it is applied to a significantly larger annual spending target. The standard calculation assumes a 4% safe withdrawal rate, which equates to multiplying your desired annual spending by 25. Alternatively, retirees can opt for a more conservative 3.5% withdrawal rate when calculating their target. When deciding on a target, individuals must carefully project their future lifestyle expectations to determine which spectrum segment aligns with their long-term comfort.
When targeting an abundant lifestyle, the required portfolio size scales rapidly with your annual spending. The table below outlines the target portfolio sizes under a standard 4% safe withdrawal rate for various high-comfort spending levels.
| Annual Spending Target | Multiplier | Required Portfolio Size (4% SWR) |
|---|---|---|
| $150,000 | 25x | $3,750,000 |
| $200,000 | 25x | $5,000,000 |
| $250,000 | 25x | $6,250,000 |
| $300,000 | 25x | $7,500,000 |
While the traditional 4% rule is a common benchmark, many early retirees opt for a more conservative approach. Your Fat FIRE number can use a more conservative 3.5% withdrawal rate applied to your larger spending target to increase the probability of portfolio survival over an extended retirement horizon.
Historical research shows that portfolio longevity is highly sensitive to initial withdrawal rates and market conditions. For example, historical cohorts that had the misfortune to begin their retirements during the 1970s stagflation experienced lower safe withdrawal rates. Conversely, research by William Bengen has estimated the highest safe initial withdrawal rate (SAFEMAX) at 4.7% under specific portfolio conditions and inflation, with optimal stock allocations ranging from 46% to 73%. However, early retirees must remain cautious as future market returns may not mirror the past. To implement this, retirees must evaluate whether their current asset allocation falls within Bengen's optimal equity range. A key decision checkpoint is whether to adjust the initial withdrawal rate downward during periods of high inflation or market volatility. Practitioners must also consider that SAFEMAX calculations assume a $1 million portfolio at retirement, with an annual inflation adjustment to the initial withdrawal dollar total and annual rebalancing. This baseline serves as a critical benchmark for testing portfolio sustainability. (Putting Morningstar’s Retirement-Income Research to the Test | Morningstar; Revisiting William Bengen’s ‘SAFEMAX’ Portfolio Withdrawal Rate | Financial Planning Association; Is 4.7% the New Safe Retirement Withdrawal Rate? - by AAII)
To illustrate the historical performance of standard withdrawal strategies, we can look at rolling 30-year periods. Even with inflation-adjusted spending starting at a 4% initial withdrawal rate, retirees finished with more than 100% of their inflation-adjusted principal 60% of the time, and doubled their real wealth almost a quarter of the time. In only 12 of 115 rolling 30-year periods from the early 1870s to the present did a retiree starting with $100,000 in an annually rebalanced 60/40 portfolio finish with less than the original principal. To apply these historical findings, retirees must decide if they are comfortable with a strategy based on historical averages. A key decision checkpoint is whether to adopt a more conservative initial withdrawal rate if current market valuations are exceptionally high. A limitation of this historical data is that past performance does not guarantee future results, and future market regimes could exhibit different patterns. Additionally, researchers have analyzed maximum 30-year withdrawal rates using historical data from the 1973–2022 half-century. (Ratcheting The Safe Withdrawal Rate For Income Upside)
One of the most significant expenses for early retirees is healthcare. Most early retirees will experience an increase in healthcare expenses between their retirement date and the age of Medicare eligibility.
Planning for these expenses is particularly valuable before reaching Medicare eligibility at age 65. Because Fat FIRE retirees have higher annual spending targets and higher withdrawal incomes, they must plan to fund these high-cost insurance premiums entirely out-of-pocket without relying on government subsidies.
Sequence of returns risk (SRR) represents the danger of market downturns occurring early in retirement. The ripple effects of inflation on annual spending can compound this risk. For instance, a retiree starting with a $40,000 withdrawal amount could find themselves spending more than $45,000 per year due to inflation, which increases their actual withdrawal rate if the portfolio balance has declined.
To mitigate this risk, retirees must monitor actual versus projected withdrawal rates to maintain financial sustainability, as adjusting withdrawal plans is essential. Depending on other sources of income, a market downturn might require belt-tightening or forgoing lavish travel plans during the first year of retirement—exactly when a retiree might prefer to spend more freely. Additionally, retirees must monitor how the ripple effects of inflation on annual spending amounts can drive up actual withdrawal rates over time, which can potentially threaten long-term portfolio survival and sustainability.
Some retirees utilize a 'ratcheting' withdrawal strategy. In the context of safe withdrawal rates, a ratcheting 4% rule can be a weakly dominant strategy over the traditional approach. While lifetime spending outcomes are not always better, they are usually better, and at worst they are merely the same. However, there is still room for further research regarding the optimal application of ratchet thresholds and the magnitude of spending increases. To implement this strategy, retirees must establish clear, objective rules for when to ratchet spending upward, such as when the portfolio value exceeds a specific threshold above its initial level. A key decision checkpoint is determining whether to apply these increases annually or at longer intervals. A primary limitation is that while this strategy prevents underspending, it does not guarantee protection against severe, prolonged market downturns, meaning retirees must still maintain a flexible mindset regarding discretionary expenses.
Building a portfolio large enough to support Fat FIRE requires maximizing tax-advantaged accounts. For high-income individuals who earn too much to contribute directly to a Roth IRA, or who have extra savings after maxing out traditional 401(k) and IRA limits, the Mega Backdoor Roth is a powerful strategy. This strategy utilizes any remaining room under overall limits, after regular contributions and employer contributions, for extra after-tax dollars that you then roll into a Roth IRA or Roth account within your 401(k). When implementing this, a key decision checkpoint is verifying whether your modified adjusted gross income exceeds the threshold for direct Roth IRA contributions. If direct contributions are restricted, this advanced method provides an alternative path to accumulate tax-free assets. However, a major limitation is that the strategy is entirely dependent on specific employer plan provisions, which must be verified before attempting any contributions. (Traditional and Roth IRA Contribution Limits | Fidelity Investments)
To take full advantage of the Mega Backdoor Roth, your employer's 401(k) plan must meet specific criteria. It must allow contributions of after-tax 401(k) dollars, and it must allow either unlimited in-plan Roth rollovers (conversions) or in-service withdrawals to an existing Roth IRA. If your plan allows after-tax contributions but does not allow immediate in-service rollovers or conversions, directing extra savings to a taxable investment account may make more sense. When implementing this strategy, savers must first contact their plan administrator to confirm these specific features are active. A key decision checkpoint is evaluating the administrative efficiency of the plan's conversion process, as delayed conversions can lead to taxable earnings. A major limitation is that not all employers offer these advanced plan features, which may force high-income savers to rely on standard taxable accounts to build their retirement nest egg.
Additionally, investors must understand the tax implications of these conversions. When executing an in-plan Roth rollover, the plan transfers the affected pre-tax catch-up contributions and attributable earnings to the participant's Roth source, and the recordkeeper issues a Form 1099-R reporting the rollover amount as taxable income. Furthermore, while state and local taxes may apply, any earnings on Roth contributions will be taxed unless the withdrawal is a qualified distribution as defined by the IRS. To implement this, savers must coordinate with their tax advisors to ensure they have sufficient liquidity outside the retirement account to cover the resulting tax liability. A key decision checkpoint is determining whether the immediate tax cost of the conversion is justified by the long-term benefit of tax-free growth. Additionally, retirees can consider the Rule of 55, an IRS provision that allows workers who separate from service at age 55 or later penalty-free access to funds held in their most recently active 401(k) or 403(b) plan. (2026 401(k) Contribution Limits: Elective Deferrals, Catch-Ups & Annual Additions; 401(k) contribution limits for 2025 and 2026)
Utilizing this IRS provision provides a crucial bridge before standard retirement account age thresholds are met. To implement this transition strategy safely, retirees must confirm that their separation from service aligns with the age requirements of the rule to secure penalty-free access to their most recently active plan.
Evidence boundary: The approved research for this guide did not answer the following questions: "Exact definition of Chubby FIRE"; "Specific tax gross-up formulas for non-sheltered accounts"; "Specific ACA subsidy phase-out thresholds for high-income early retirees"; "HSA contribution limits and specific triple-tax-advantaged rules for Fat FIRE" Confirm each point against current primary guidance and any relevant plan rules before acting.
Use 8FIGURES to inspect your portfolio inputs and prepare better questions for your own review.
Managing your investments has never been easier!
